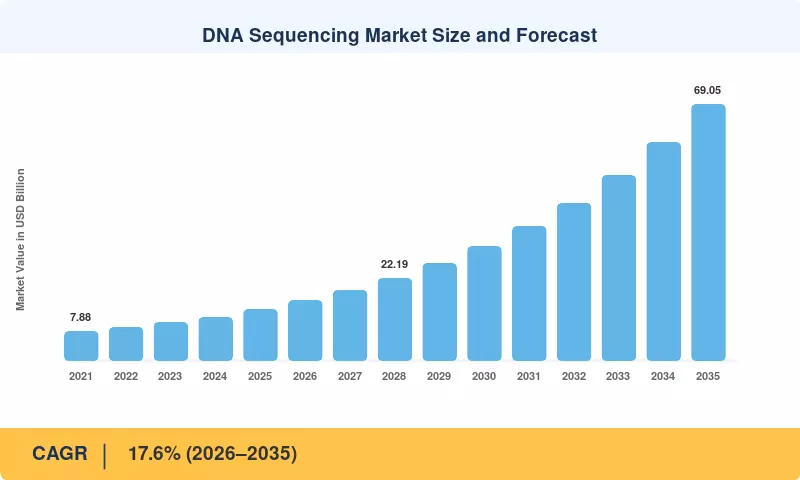
DNA Sequencing Market to Surge from USD 13.65 Billion in 2025 to USD 69.05 Billion by 2035—Driven by Declining Cost Per Genome, Reimbursement Expansion
NY, CA, UNITED STATES, September 16, 2026 /EINPresswire.com/ — As per Market Research Future, the global DNA Sequencing Market size is projected to reach USD 69.05 Billion by 2035 from USD 13.65 Billion in 2025, at a CAGR of 17.6% during the forecast period 2026–2035. The market base was estimated at USD 13.65 Billion in 2025.
The 17.6% CAGR—anchored by structural shifts in genomic medicine and molecular diagnostics—is propelled by three converging forces: the declining cost per genome, which has fallen from roughly USD 1,000 in 2019 to under USD 200 on high-output configurations by 2024, converting marginal research questions into funded projects and enabling hospital laboratories to justify capital purchases on throughput alone; reimbursement expansion for comprehensive genomic profiling, with the U.S. Centers for Medicare & Medicaid Services establishing a reimbursable pathway worth an estimated USD 1.9 billion in annual U.S. testing spend by 2025, converting discretionary research purchases into billable clinical services; and national precision-medicine and population genomics programmes, including Genomics England’s GBP 105 million Newborn Genomes Programme and India’s Genome India initiative, which have moved public money from pilot cohorts into standing testing infrastructure.
Global sequencing platform vendors and health organizations are amplifying this momentum. Illumina, the incumbent scale leader, continues advancing next-generation sequencing platforms and informatics solutions including DRAGEN 4.3 with multi-genome graph mapping. Thermo Fisher Scientific leverages its broad life-science channel with clinical panel focus through the Ion Torrent Genexus platform. BGI Genomics / MGI Tech anchors the Asia-Pacific market with cost-led DNBSEQ platforms. According to WHO data, more than 90 countries had established national sequencing nodes by 2024 under the Global Genomic Surveillance Strategy. These forces are creating the clinical infrastructure and research demand on which the DNA Sequencing Market depends.
Request A Free Sample:
https://www.marketresearchfuture.com/sample_request/5774
Key Market Trends & Growth Drivers
Declining Cost Per Genome and Installed-Base Expansion
The market is witnessing a sustained decline in the cost per genome, falling more than 80% from 2019 levels. As sequencing economics continue to improve, more hospital laboratories and research institutions are justifying capital purchases on throughput alone. This trend indicates a shift from discretionary research purchases to routine clinical infrastructure, with each installed instrument locking in multi-year consumable pull-through. Illumina continues advancing platform economics through NovaSeq X and MiSeq i100 innovations, while Pacific Biosciences’ SPRQ chemistry pushed HiFi human genome cost below USD 500.
Reimbursement Expansion for Comprehensive Genomic Profiling
Payer decisions are converting clinical interest into billable volume across the DNA Sequencing Market. The CMS National Coverage Determination for next-generation sequencing in advanced cancer, together with subsequent expansion to germline testing, established a reimbursable pathway worth an estimated USD 1.9 billion in annual U.S. testing spend by 2025. European statutory insurers followed with tumour-profiling tariffs in Germany and France. This reimbursement momentum is transforming sequencing from a research tool into a standard-of-care diagnostic service.
National Precision-Medicine and Population Genomics Programmes
The incorporation of sovereign genomics budgets into national healthcare infrastructure is gaining traction. Genomics England committed GBP 105 million to sequence 100,000 newborns, while India’s Genome India initiative completed reference sequencing of 10,000 individuals across 83 population groups. Saudi Arabia’s Genome Program and China’s provincial biobank projects add comparable volume. These programmes standardise consent, storage, and interpretation frameworks that private laboratories subsequently inherit at lower cost, creating standing demand that is insensitive to research funding cycles.
Oncology Diagnostics and Residual-Disease Monitoring
Cancer care supplies the highest-frequency clinical use case in the DNA Sequencing Market. Clinical Diagnostics overtook research spending for the first time in 2025, generating USD 6.47 billion, with Oncology the dominant sub-application growing at a 17.8% CAGR. Molecular residual-disease assays extend testing from a single diagnostic event to quarterly surveillance, multiplying lifetime revenue per patient and shifting laboratory workload toward recurring, protocol-driven runs.
Ask for Customization:
https://www.marketresearchfuture.com/ask_for_customize/5774
Market Segment Insights
BY PRODUCT & SERVICE
Consumables: Largest segment with 54.2% share in 2025, sustained by proprietary flowcell and reagent-kit reordering that cannot be substituted across platforms. Gross margin on reagents consistently exceeds margin on hardware.
Instruments: Significant share at 30.6% in 2025, driven by installed-base expansion in hospital laboratories. Instruments function largely as a channel to recurring consumable revenue.
Services: Fastest-growing segment, expanding at a 16.8% CAGR through 2035, as laboratories outsource interpretation, storage, and regulatory reporting rather than hiring scarce bioinformatics staff.
BY SEQUENCING TECHNOLOGY
Next-Generation Sequencing: Dominant technology with 76.1% share in 2025, anchored by validated clinical workflows, broad assay menus, and payer familiarity accumulated over a decade.
Nanopore Sequencing: Fastest-growing technology, rising at a 25.9% CAGR over 2026–2035, addressing repeat expansions, phasing, and native methylation in a single run that short reads cannot resolve.
Sanger Sequencing: Retains a durable confirmatory niche with 9.8% share in 2025, as regulators in several jurisdictions still expect orthogonal validation of reportable variants.
BY WORKFLOW STEP
Sequencing: Dominant workflow step with 42.2% share in 2025, capturing run volume growth across clinical and research channels.
Data Analysis and Storage: Fastest-growing step, climbing at a 20.7% CAGR, as reimbursement increasingly pays for an actionable report rather than a raw file, and multi-omics file sizes compound storage demand.
Sample Preparation: Generated USD 3.73 Billion in 2025, benefiting from low-input, multichannel library kits that reduce hands-on time.
BY APPLICATION
Clinical Diagnostics: Largest segment with 47.4% share in 2025, overtaking research use for the first time, driven by oncology profiling, rare disease, and reproductive health applications.
Research Applications: Generated USD 5.43 Billion in 2025, sustained by grant-funded discovery and population studies, though growing more slowly than reimbursed clinical testing.
Other Applications: Fastest-growing application category at a 16.2% CAGR, spanning forensics, agrigenomics, and consumer wellness testing.
BY END USER
Academic Institutions: Largest segment with 37.4% share in 2025, controlling demand through grant-funded single-cell and spatial-omics workflows that pilot methods later becoming routine.
Hospitals & Clinical Laboratories: Fastest-growing end-user segment at a 15.7% CAGR, as turnkey platforms simplify validation and reporting, shortening accreditation timelines from months to weeks.
Pharmaceutical & Biotechnology Companies: Contributed USD 3.40 Billion in 2025, driven by target discovery and companion-diagnostic development programmes.
Read Detailed Insights:
https://www.marketresearchfuture.com/reports/dna-sequencing-market-5774
Regional Outlook
North America — Market Leader in Innovation
North America leads with over 41.6% of global revenue in 2025, generating around USD 5.68 Billion. The region’s growth is driven by mature payer coverage, NIH extramural funding, and FDA authorisations for companion diagnostics that give laboratories defensible reporting standards. According to CMS data, the National Coverage Determination for next-generation sequencing in advanced cancer established a reimbursable pathway worth an estimated USD 1.9 billion in annual U.S. testing spend by 2025. The competitive landscape is characterised by continuous platform innovation and strategic partnerships among leading sequencing vendors.
Europe — Second Largest Market
Europe contributed USD 3.47 billion in 2025, representing the second-largest regional market. The region benefits from programme-led growth rather than payer-led expansion. Genomics England committed GBP 105 million to newborn sequencing, while France Médecine Génomique built a national platform network with defined referral criteria. Germany’s statutory insurers reimburse tumour profiling under negotiated tariffs. Regulatory bodies like the EMA are actively facilitating the approval of new sequencing-based diagnostics. Leading countries include Germany, the UK, and France, where major platform vendors such as Roche and QIAGEN are heavily invested.
Asia-Pacific — Rapidly Growing Market Segment
The Asia-Pacific region is expected to experience the highest growth rate at a 20.3% CAGR through 2035. The growth is driven by provincial tumour-profiling mandates in China, India’s Genome India rare-disease screening rollout, and Japan’s designated cancer genomic medicine hospitals. Domestic manufacturing is a large part of the reason—Chinese platform vendors supply instruments at prices that undercut imports, while the 2025 restriction on specified foreign sequencers accelerated local substitution. The competitive landscape is evolving with companies like BGI Genomics / MGI Tech and Oxford Nanopore Technologies leading the charge.
Middle East and Africa — Untapped Potential
The MEA region is projected to grow at a 15.8% CAGR through 2035, driven by sovereign genome programmes and pathogen surveillance mandates. Saudi Arabia’s Human Genome Program and the UAE’s Emirati Genome Programme both procure at national scale with multi-year commitments. Sub-Saharan capacity grew largely through pathogen surveillance investment, with more than 90 countries operating national sequencing nodes by 2024 under the WHO Global Genomic Surveillance Strategy. Countries like South Africa and the UAE are leading the way, with a growing presence of international sequencing service providers.
South America — Emerging Opportunity
South America was valued at USD 0.59 Billion in 2025. Brazil dominates regional demand through a combination of large private laboratory groups and gradual public-sector adoption within SUS oncology pathways. Currency exposure on imported reagents remains the binding constraint; laboratories hedge by holding larger inventory, which raises working-capital requirements. Argentina’s activity concentrates in paediatric rare-disease referral centres. Across the region, sample export to North American and European reference laboratories still absorbs a meaningful share of clinical volume, limiting domestic installed-base growth.
Competitive Landscape and Recent Developments
The DNA sequencing market is characterised by intense competition and rapid growth, driven by declining sequencing costs and expanding clinical applications worldwide. The global industry appears moderately concentrated, with the top five suppliers accounting for roughly 61–66% of global revenue and a single vendor holding more than a third.
KEY COMPANIES AND RECENT MILESTONES
Illumina (US): Holds an estimated 34–39% revenue share as the incumbent scale leader. In January 2025, released DRAGEN 4.3 with multi-genome graph mapping, cutting reference bias in variant calling. In February 2025, launched MiSeq i100 with four-hour runs and ambient-temperature reagents, enabling same-day pathogen detection. In June 2024, completed the GRAIL spin-off, resolving a prolonged antitrust dispute and refocusing capital on core platform and informatics investment.
Thermo Fisher Scientific (US): Holds an estimated 11–14% revenue share. Leverages its broad life-science channel with clinical panel focus through the Ion Torrent Genexus platform and Applied Biosystems Sanger systems, serving both research and diagnostic end users.
BGI Genomics / MGI Tech (CN): Holds an estimated 6–9% revenue share. Anchors the Asia-Pacific market with cost-led DNBSEQ platforms and sequencing services, benefiting from domestic substitution policies and provincial laboratory network expansion.
Oxford Nanopore Technologies (UK) (May 2024): Shipped PromethION 2 Integrated with onboard compute and 290 Gb per flowcell output, strengthening the clinical case for long-read adoption. Holds an estimated 4–6% revenue share as the long-read pioneer targeting real-time clinical use.
Pacific Biosciences (US) (October 2024): Introduced SPRQ chemistry, pushing HiFi human genome cost below USD 500 and improving the economics of long-read population studies. Holds an estimated 2–4% revenue share as the HiFi accuracy leader.
Roche (CH) (February 2025): Unveiled sequencing-by-expansion (SBX) chemistry, signalling a credible platform re-entry by a major diagnostics incumbent and intensifying consumable price competition. Holds an estimated 3–5% revenue share.
Other Key Players: QIAGEN (DE), Agilent Technologies (US), Eurofins Genomics (LU), Element Biosciences (US), Ultima Genomics (US).
Future Outlook: 2026–2035
The DNA Sequencing Market is projected to reach USD 69.05 billion by 2035, growing at a CAGR of 17.6%, driven by declining cost per genome, expanding reimbursement coverage, and national precision-medicine programmes.
New opportunities lie in:
Sequencing-as-a-Service and managed informatics converting capital costs into operating models
Emerging-market capacity building across Asia-Pacific, Latin America, and Gulf health systems
Genomic data monetization and real-world evidence through consented, longitudinally annotated cohorts
Rapid and point-of-care clinical sequencing with four-hour run chemistries for same-day pathogen identification
Multi-omics and spatial integration raising revenue per specimen and increasing switching costs
By 2035, the DNA Sequencing Market is expected to achieve substantial growth and innovation, with clinical diagnostics permanently overtaking research as the primary demand driver and interpretation services capturing an increasing share of total value.
More Related Research Insights:
https://www.marketresearchfuture.com/fr/reports/healthcare-digital-twin-market-31239
https://www.marketresearchfuture.com/ja/reports/healthcare-digital-twin-market-31239
https://www.marketresearchfuture.com/de/reports/healthcare-digital-twin-market-31239
https://www.marketresearchfuture.com/es/reports/healthcare-digital-twin-market-31239
https://www.marketresearchfuture.com/zh-cn/reports/healthcare-digital-twin-market-31239
https://www.marketresearchfuture.com/ko/reports/healthcare-digital-twin-market-31239
https://www.marketresearchfuture.com/fr/reports/home-healthcare-market-2030
https://www.marketresearchfuture.com/ja/reports/home-healthcare-market-2030
https://www.marketresearchfuture.com/de/reports/home-healthcare-market-2030
https://www.marketresearchfuture.com/fr/reports/human-platelet-lysate-market-37130
Market Research Future
Market Research Future
+1 855-661-4441
email us here
Legal Disclaimer:
EIN Presswire provides this news content “as is” without warranty of any kind. We do not accept any responsibility or liability
for the accuracy, content, images, videos, licenses, completeness, legality, or reliability of the information contained in this
article. If you have any complaints or copyright issues related to this article, kindly contact the author above.

Media gallery